
ESG Reporting Germany
ESG reporting documents how a company addresses environmental, social and governance matters and the associated risks. Reports can cover emissions, working conditions, governance arrangements and other material information. The applicable framework determines the subjects, measurements and disclosures that an organization must provide.
Investors, lenders and supervisors use sustainability information to assess companies and financial products. Corporate reporting, bank disclosures on ESG risks and fund disclosures under the SFDR serve different purposes. Reliable reporting requires traceable data and an explanation of how the figures relate to the business or investment portfolio.
What ESG reporting means for companies and banks in Germany
ESG reporting is the disclosure of environmental, social and governance information next to the financial statements: emissions, energy use, staff, supply chains, board oversight. In EU law the term is sustainability reporting. The main law is the Corporate Sustainability Reporting Directive (CSRD), Directive (EU) 2022/2464, and the content is set by the European Sustainability Reporting Standards (ESRS).
For finance, three more EU rules sit on top. Banks disclose ESG risks in their Pillar 3 reports under the Capital Requirements Regulation. Asset managers and insurers disclose how their funds treat sustainability under the Sustainable Finance Disclosure Regulation (SFDR). The EU Taxonomy Regulation decides which economic activities count as environmentally sustainable, and both companies and financial firms report the share of their business that meets it.
Where the German CSRD transposition stands
An EU directive only binds a company once a member state writes it into national law. In Germany that law is the CSRD Implementation Act (CSRD-Umsetzungsgesetz, CSRD-UmsG). The federal cabinet adopted a government draft, the Bundestag held its first reading and a public hearing, and no second and third reading has taken place so far. Until the law passes, German companies report under the older CSR Directive Implementation Act (CSR-RUG), which put the Non-Financial Reporting Directive into the German Commercial Code. The German standard setter DRSC and the auditors' institute IDW consider a retroactive start of the new rules constitutionally questionable.
The EU scope has shrunk in the meantime. The Omnibus I package, Directive (EU) 2026/470, limits mandatory CSRD reporting to companies with more than 1,000 employees and more than EUR 450 million net turnover. Both tests must be met. Suppliers with up to 1,000 employees may decline to hand their large customers more data than the voluntary standard asks for. For many German Mittelstand firms the CSRD omnibus therefore turns a legal duty into a request from their bank or their customers.
The standards: ESRS, ISSB and who writes them
The ESRS are drafted by EFRAG in Brussels and adopted by the European Commission as delegated acts. The Commission has published the simplified ESRS together with a voluntary standard for companies outside the scope. With the simplified ESRS, a company may, for a transition year, choose between the old set, the new set, or the old set with selected flexibilities from the new one, and it must say which one it used.
In Germany, the Accounting Standards Committee of Germany (DRSC) in Berlin represents German preparers and users in this process. The DRSC's members come in segments for listed industrial companies, banks and insurers. Outside the EU framework, the International Sustainability Standards Board (ISSB) writes the IFRS sustainability standards used in many other markets. The ISSB's Frankfurt office stays the hub for its EU engagement, while the IFRS Foundation opens a new ISSB seat in Geneva.
ESG reporting at banks, asset managers and the Bundesbank
Banks report twice: on their own business and on the ESG risks in the loans and bonds they hold. The EBA has revised the Pillar 3 templates for ESG risks: 37 percent fewer datapoints for large institutions and 84 percent fewer for small and non-complex ones, whose figures the EBA will pre-fill in its Pillar 3 Data Hub. Supervision has teeth as well. The ECB imposed periodic penalty payments of EUR 187,650 on the Spanish bank ABANCA because it missed a deadline for a materiality assessment of its climate and environmental risks by 65 days.
Fund managers watch the SFDR 2.0 proposal. The Commission wants to replace the familiar Article 8 and Article 9 labels with three product categories: Transition, ESG Basics and Sustainable. Each requires at least 70 percent of the portfolio to meet the category, and only funds in a category may use sustainability terms in their name or marketing. The EU taxonomy simplification brought a 10 percent materiality threshold and shorter templates, and financial firms may postpone their taxonomy KPIs. Since the ESG Ratings Regulation took effect, ESMA authorizes and supervises the providers of the ESG ratings that many of these reports rely on.
The German central bank reports on itself too. The Deutsche Bundesbank publishes annual climate-related disclosures on its own investments and on transition risks in the German financial system. The Bundesbank's latest report shows for the first time the financed emissions of commercial banks whose bonds it holds, and it finds the German financial system resilient to transition risks overall.
Who works on ESG reporting in Germany
In Frankfurt, the Sustainable Finance Cluster was formed from Deutsche Börse's Accelerating Sustainable Finance Initiative and the Green Finance Cluster Frankfurt of the Hessian Ministry of Economics, and it is the point of contact on sustainable finance for banks, companies, academia and politics. Frankfurt School of Finance & Management runs executive programs and certificates in sustainable finance and ESG.
Someone new to the field should learn the ESRS double materiality logic first, then the Pillar 3 or SFDR templates of their own sector, and then the data systems that feed them.
Upcoming finance events in Germany
Finance Loop, the meeting place for ESG reporting and sustainable finance
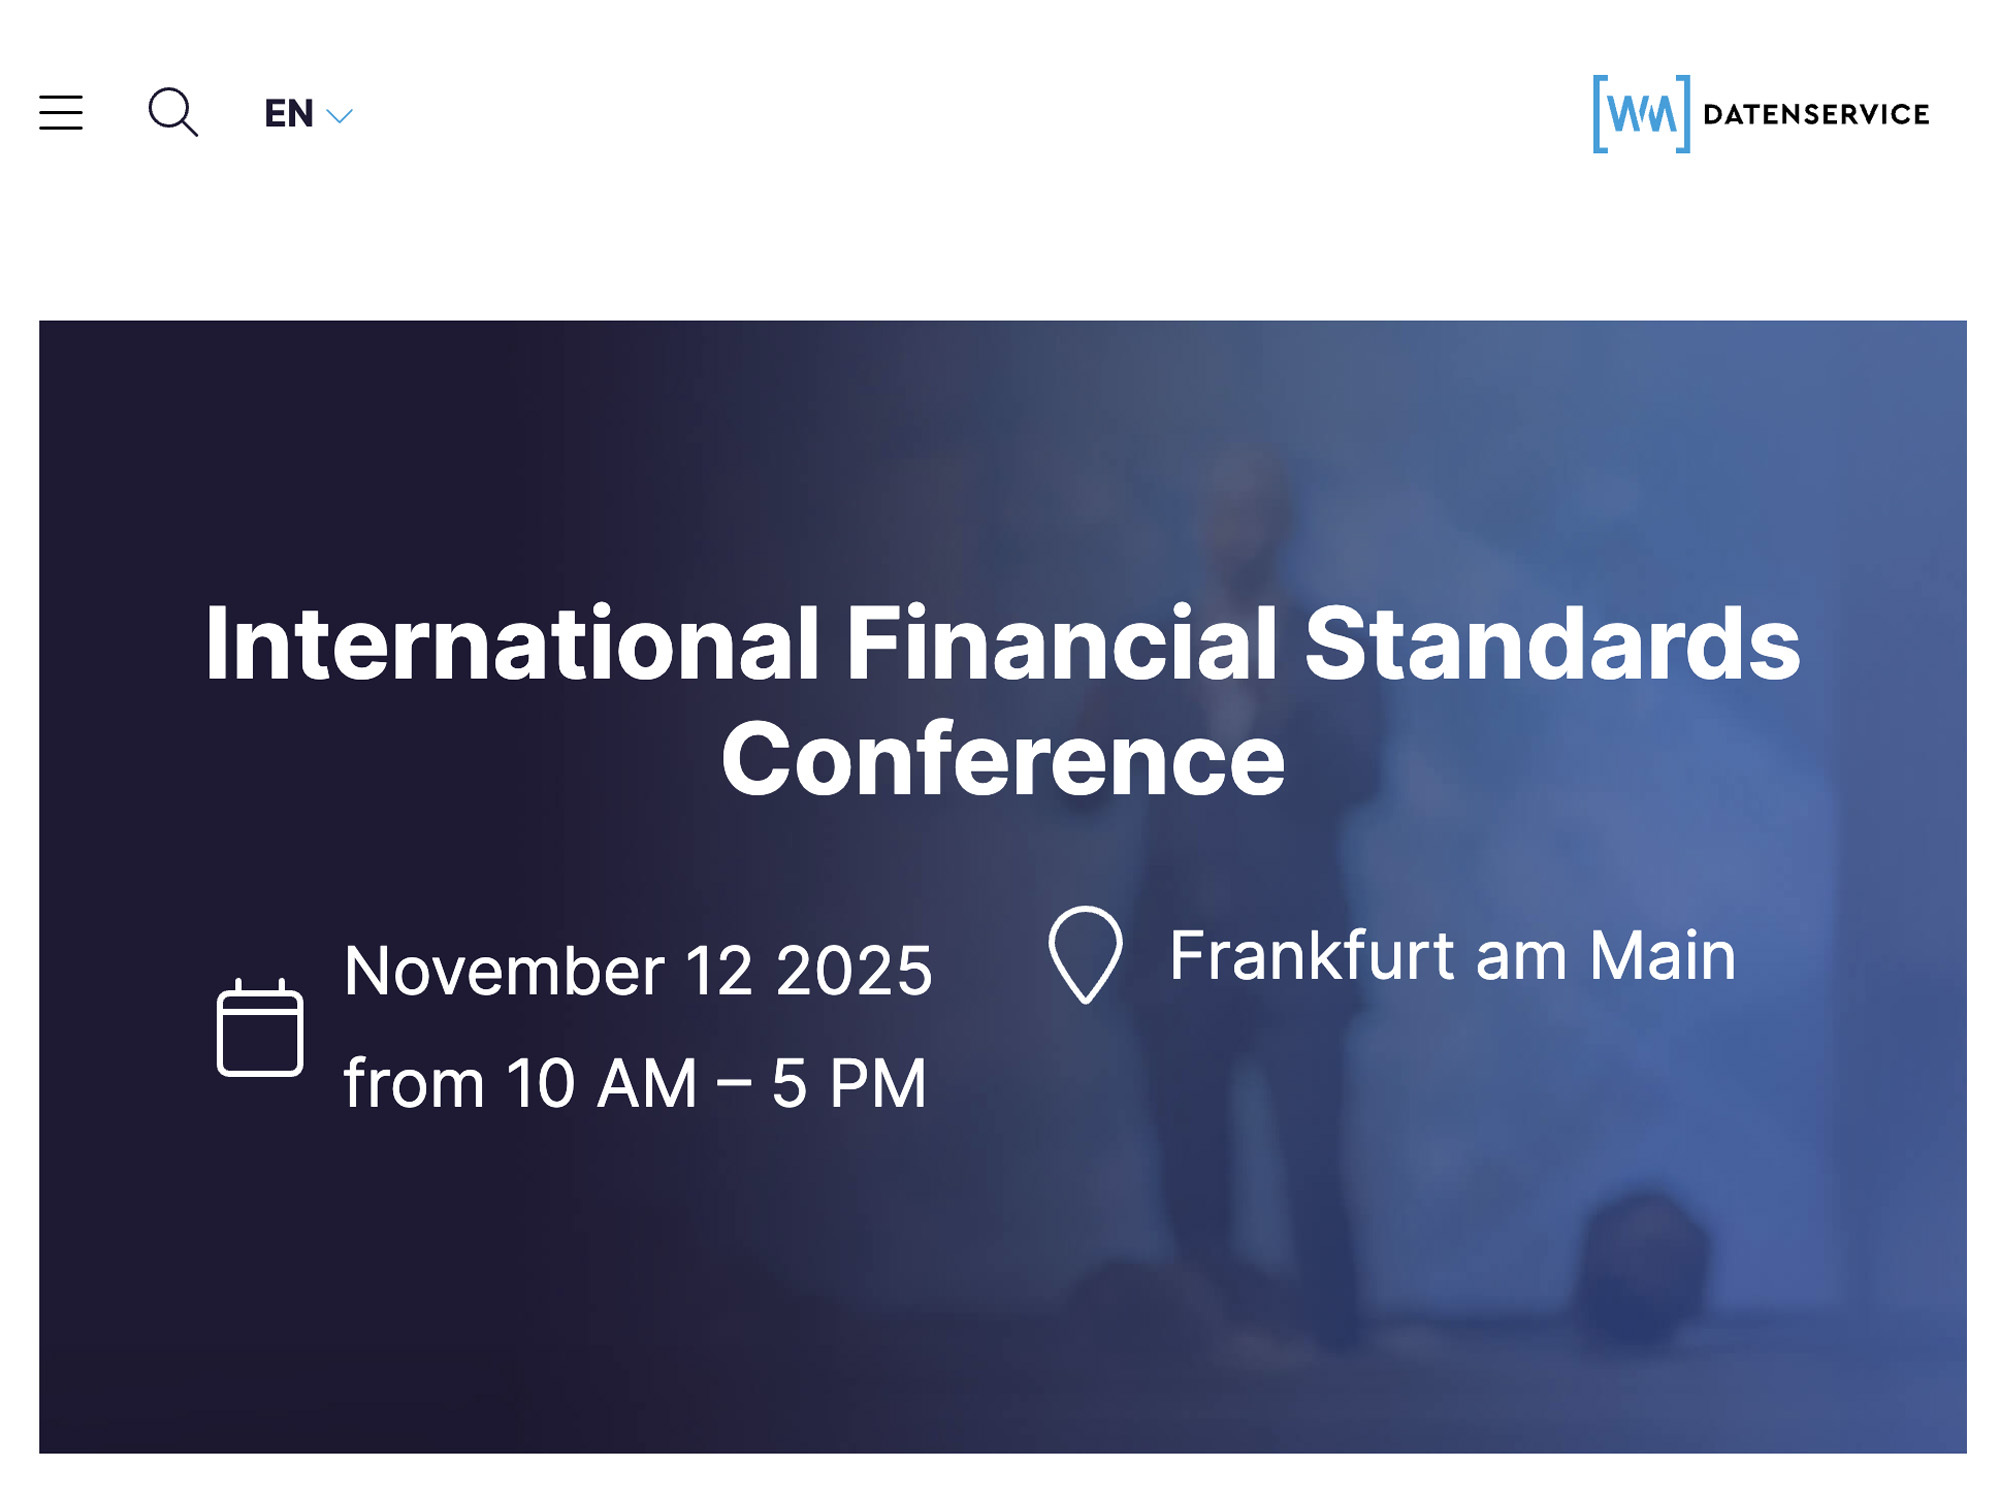
Finance Loop is the meeting place for the people who build these reports: risk managers, controllers, data teams and the regtech firms that serve them. Finance Loop was media partner of the International Financial Standards Conference of Börsen-Zeitung in Frankfurt, where regulators, standard setters, auditors and financial leaders discussed financial reporting and ESG disclosure. Finance Loop's strategic partner Frankfurt Main Finance counts sustainable finance among its focus areas. Finance Loop is built in collaboration with TechQuartier. Finance Loop's events take place in Frankfurt and also in Munich, Berlin and Hamburg.
Related pages on this site: DORA in Germany.
What are the ESG reporting requirements in Germany?
A German company reports under the CSR-RUG rules in the Commercial Code until the CSRD-Umsetzungsgesetz passes. Mandatory CSRD reporting will cover companies with more than 1,000 employees and more than EUR 450 million net turnover. Banks add ESG disclosures in their Pillar 3 reports, and asset managers add SFDR and taxonomy disclosures for their funds.
Has Germany transposed the CSRD?
No. The government draft of the CSRD-Umsetzungsgesetz passed the cabinet and a first reading in the Bundestag, and a public hearing followed, but the Bundestag has not adopted it. The Omnibus I directive gives member states a new deadline to transpose the amended rules.
What is the difference between ESG reporting and sustainability reporting?
In practice the two mean the same disclosure. "Sustainability reporting" is the legal term in the CSRD and the ESRS. "ESG reporting" is the term investors, rating agencies and banks use, and it often refers to the environmental, social and governance data that feed a rating or a Pillar 3 template.
Where can you learn ESG reporting in Frankfurt?
Frankfurt School of Finance & Management offers executive programs and certificates in sustainable finance and ESG. The Sustainable Finance Cluster brings banks, companies and academia together on the topic. At Finance Loop events you meet the people from banks and fund houses who do this work every day.
Finance Loop and ESG reporting
Finance Loop connects the finance, IT and AI communities. An ESG report needs people from finance who own the numbers and people from IT who build the data flows behind them.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, digital payments, cloud and blockchain solutions. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.