
Digital wallet Germany
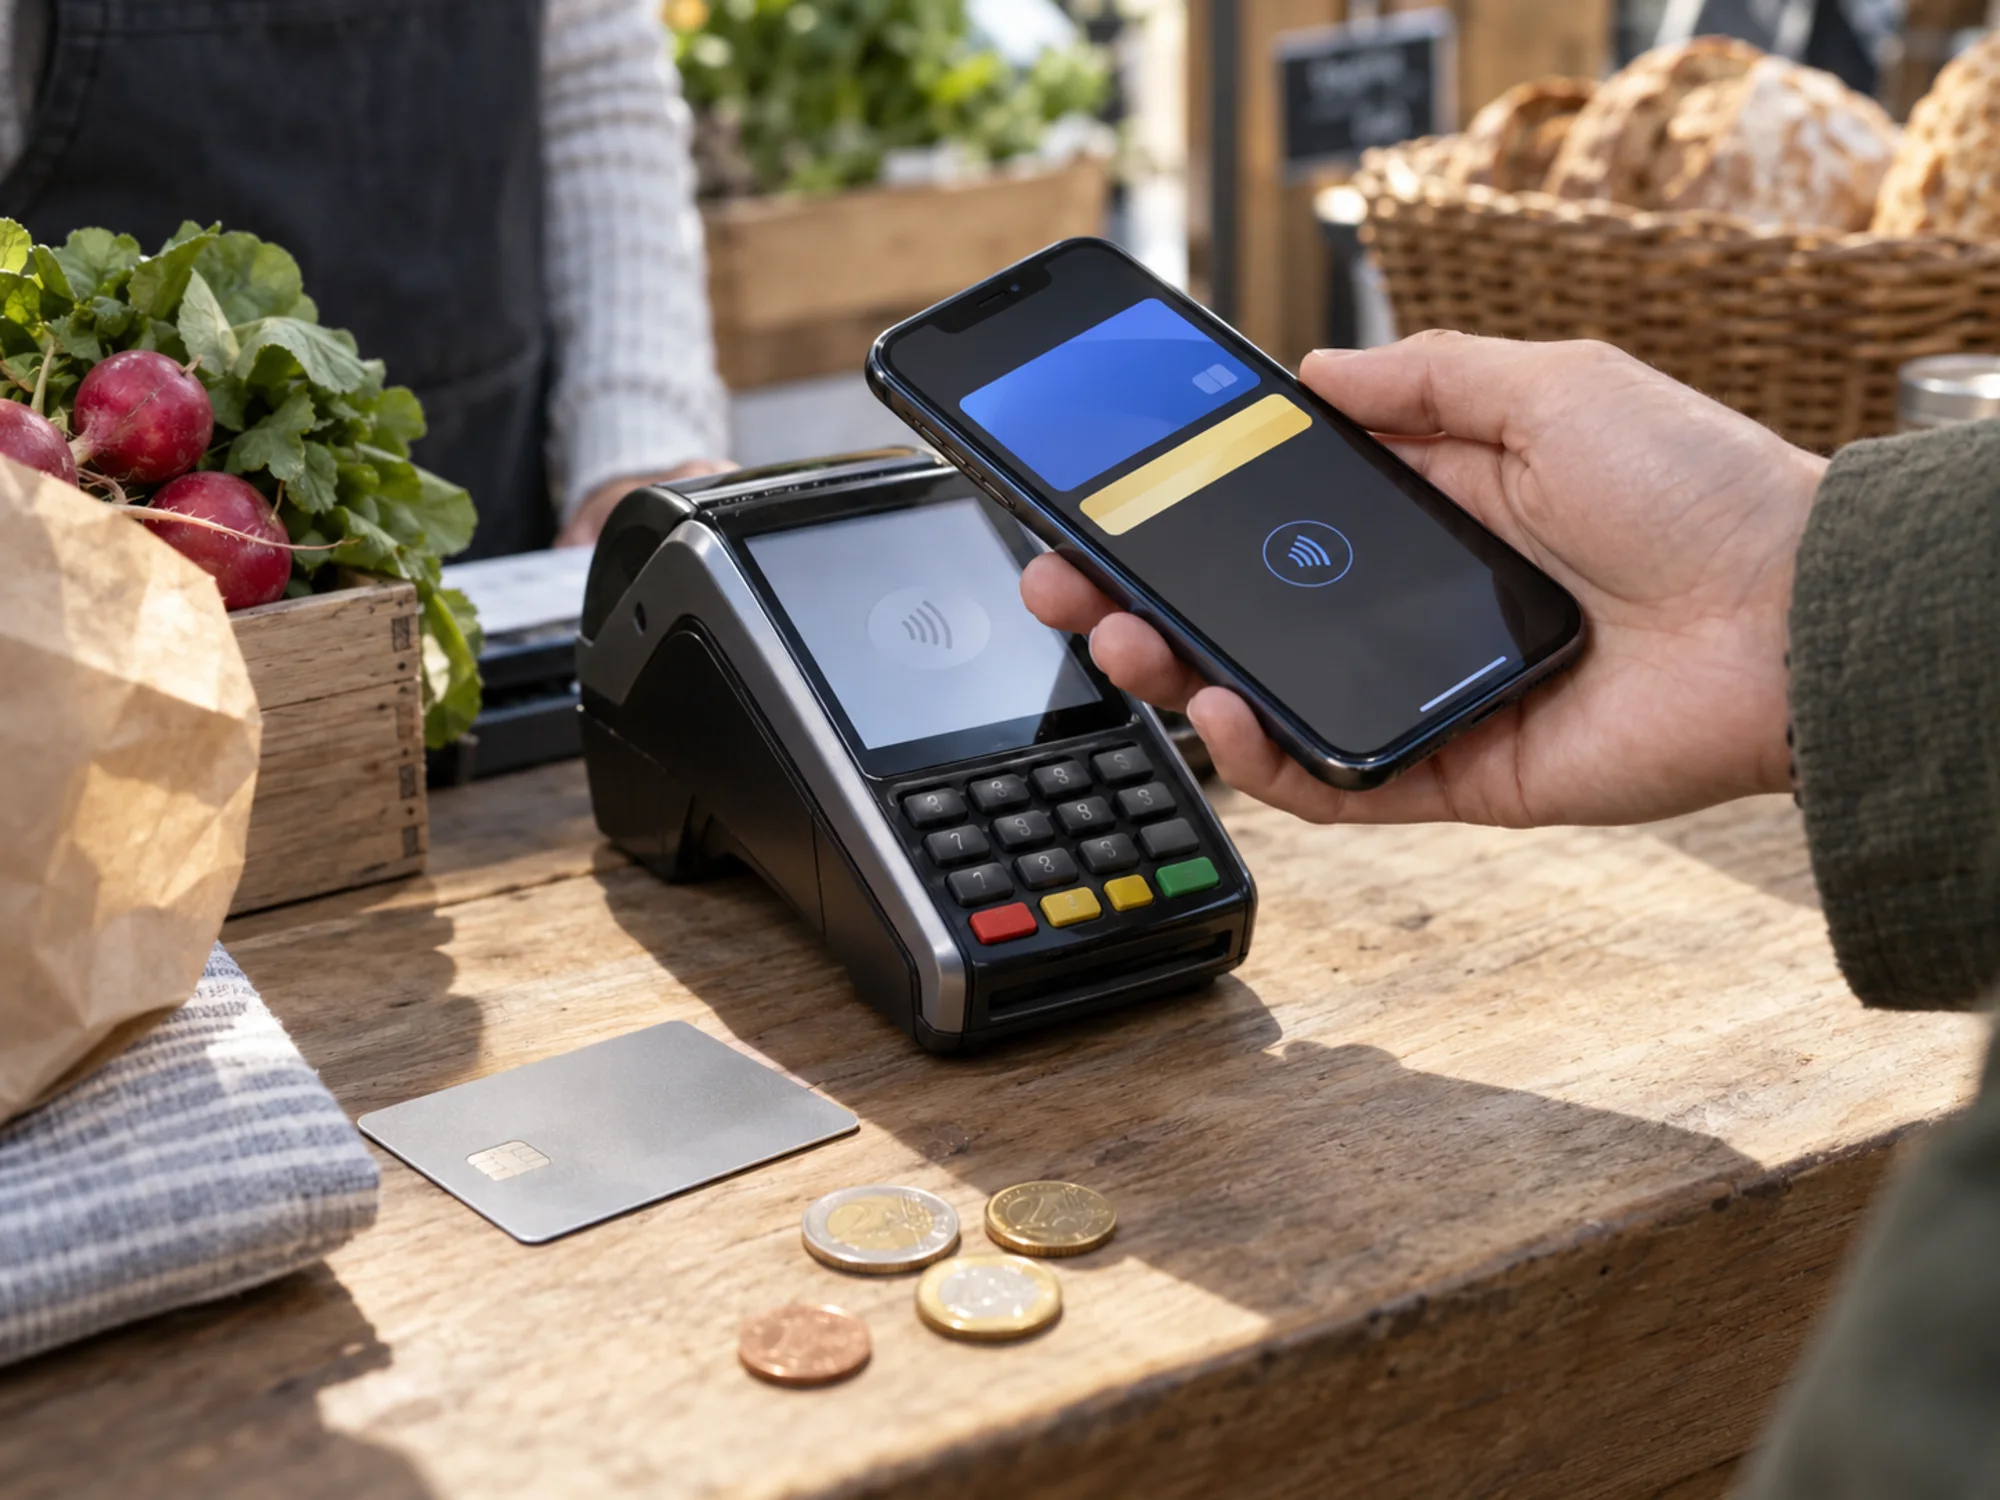
A digital payment wallet is an app or service that lets a customer use stored payment details to pay online or at a checkout. A wallet can connect to a payment card, a bank account or a balance held with the provider. The customer uses a phone, watch or another supported device to choose the payment method and confirm the purchase.
Digital wallets make payment details available when needed without requiring the customer to enter them for every purchase. The underlying card, transfer or stored-value system determines how the money reaches the merchant. Banks, wallet providers and merchants therefore need to coordinate payment acceptance, authentication and the handling of customer funds.
What the wallet holds, and what moves the money
A wallet stores a payment credential and provides a way to prove that the holder is present. The credential can be a tokenized card number, a mandate to debit a bank account, or a key over a stablecoin balance. Authentication is the phone's own biometry or PIN, which in a card payment satisfies the strong customer authentication that European payment rules require.
Money then travels on whichever rail the credential belongs to. A card credential runs through the card network and the acquirer, so the fees are card fees, described on card payments in Germany. A bank-account credential runs as a transfer, usually an instant one, covered on instant payments in Europe. A stablecoin credential settles on a blockchain, which stablecoin payments sets out. The wallet brand on the screen tells you nothing about which of the three you are on.
Staged wallet or pass-through wallet: the distinction that decides your license
A pass-through wallet passes the shopper's payment credential to the merchant, who clears it with their own acquirer; the wallet operator never holds the funds. Apple Pay and Google Pay work this way over Visa and Mastercard tokens. A staged wallet splits one purchase into two card transactions, a funding stage where the customer loads a balance and a payment stage where the wallet pays the merchant, and in both of them the charge comes from the wallet operator and not from the store, as the payment-provider documentation on staged digital wallet operators describes it.
Holding customer money before a purchase is the business of an e-money or payment institution and needs a BaFin license, which payments regulation in Germany covers. The card networks also treat the two forms differently: a staged operator has to register a wallet identifier with each network, because without it the network cannot see the individual purchase behind the loaded balance. A pass-through design avoids both of those, at the price of giving up control over the funding step.
Card tokenization inside a phone wallet
When a card goes into a phone wallet, the wallet does not store the printed card number. The phone wallet stores a token that is restricted to that device, and the device adds a one-time cryptogram per payment. A stolen token is therefore worth little outside the phone it was issued to. The mechanics, and how a payment token differs from an encrypted card number, are on what tokenization in payments is.
Tokenization is also what lets a bank keep the customer relationship in someone else's wallet. The issuing bank authorizes the token, can suspend it, and sees the transaction. That is the difference from a staged wallet, where the bank sees a load to the wallet operator and not the shop the customer went to.
The wallets people pay with in Germany
Germany still pays largely by card and by invoice, and the wallet layer sits on top of that instead of replacing it. Apple Pay and Google Pay are front ends over tokenized Visa and Mastercard credentials. PayPal came from the e-commerce checkout and has moved to the physical store: its German wallet pilot lets customers tap to pay wherever Mastercard contactless is accepted, which means it needed no new terminals, as PaymentsJournal reports. Wero is the account-to-account wallet of the European banks, described on Wero payments in Germany.
A German trade overview puts mobile payments from phones and watches at about 5.7 percent of all payments in 2024, roughly twice the share of five years earlier, as Ecommerce Germany collects it. The consumer barometer from the European Payments Initiative counts habit instead of volume: a third of people in Germany use a mobile payment app at least weekly, and 19 percent reach for a wallet on a phone or watch in a physical shop, per the EPI barometer. Both readings point the same way: the wallet is normal for a minority of payments and a second option for most.
Wallet interoperability: why one integration per wallet does not scale
Every wallet a merchant adds is its own integration, with its own rules and its own terms. With a handful of wallets that is a project; with a wallet per bank group and per country it stops being affordable, and the smallest merchants simply do not do it. Interoperability is the attempt to make the merchant integrate a protocol instead of a brand, so that any conforming wallet can present at that checkout.
This is where the European identity wallet touches payments. The European identity wallet's architecture fixes the formats and protocols between the party issuing a credential, the wallet holding it and the party checking it, so a verifier builds once for every conforming wallet in the Union. The same shape is what a payment checkout wants, and the EUDI Wallet explains the framework and its deadlines.
Is a crypto wallet the same thing?
A crypto wallet holds the private keys that control coins on a blockchain, and losing the keys loses the coins. A payment wallet holds a credential that points at money held somewhere else, at a bank or an issuer, and a lost phone is replaced without losing the money. What a private key does is explained on what a crypto wallet is, the device question on hardware wallets, the backup question on private key versus seed phrase, and the German market on bitcoin wallets in Germany.
A wallet app that offers both a card credential and a stablecoin balance is a payment wallet and a crypto wallet at once, and each half brings its own license: payment services for the card and the e-money token, crypto-asset services for the custody. Crypto custody in Germany covers the second half.
Will a digital wallet become compulsory in Germany?
No rule requires a person in Germany to pay from a wallet, and cash and cards stay available. The obligations in European law run the other way: they apply to member states and to large service providers, not to shoppers. The identity wallet the German state is building is explicitly voluntary to use, (German EUDI Wallet).
What are the drawbacks of paying by digital wallet?
A wallet depends on a charged device and, for most products, on a network connection at the till. The digital wallet also adds a party between the customer and the bank, and in a staged wallet that party holds the money for a while, so the customer carries the operator's risk and not only the bank's. The third drawback is data: whoever runs a wallet sees the pattern of purchases, which is the reason the European identity wallet was designed to keep credentials on the device with no central collection.
Which digital wallets can a German merchant accept?
A German merchant usually accepts the phone wallets through its existing card acceptance, because Apple Pay and Google Pay arrive as contactless Visa and Mastercard transactions on the terminal it already has. PayPal and Wero are separate contracts, PayPal as a checkout and in-store wallet, Wero as an account-to-account product of the banks. Payments in Germany sets out who runs which rail.
Digital wallets and the Finance Loop network
Finance Loop is the meeting place for the payment people who build and buy wallet products in Germany: the card and account rails first, stablecoin rails next. Finance Loop runs events in Frankfurt, Berlin, Munich and Hamburg where issuers, acquirers, payment institutions and wallet providers sit in the same room, and the wallet question belongs to its Payments & Digital Money track.
Finance Loop is a professional network supporting the institutional use of emerging technologies in finance, such as AI, tokenization, stablecoins, and DeFi. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, Digital Infrastructure & Sovereignty, and Risk & Compliance.