
Issue tokenized securities in Germany
A company issuing a bond in Germany can use an electronic security instead of a paper certificate. The legal terms, investor rights, register and distribution route still have to work together. Gubbi AG supports that process; its GDX Primary Market addresses placement through regulated distribution channels.
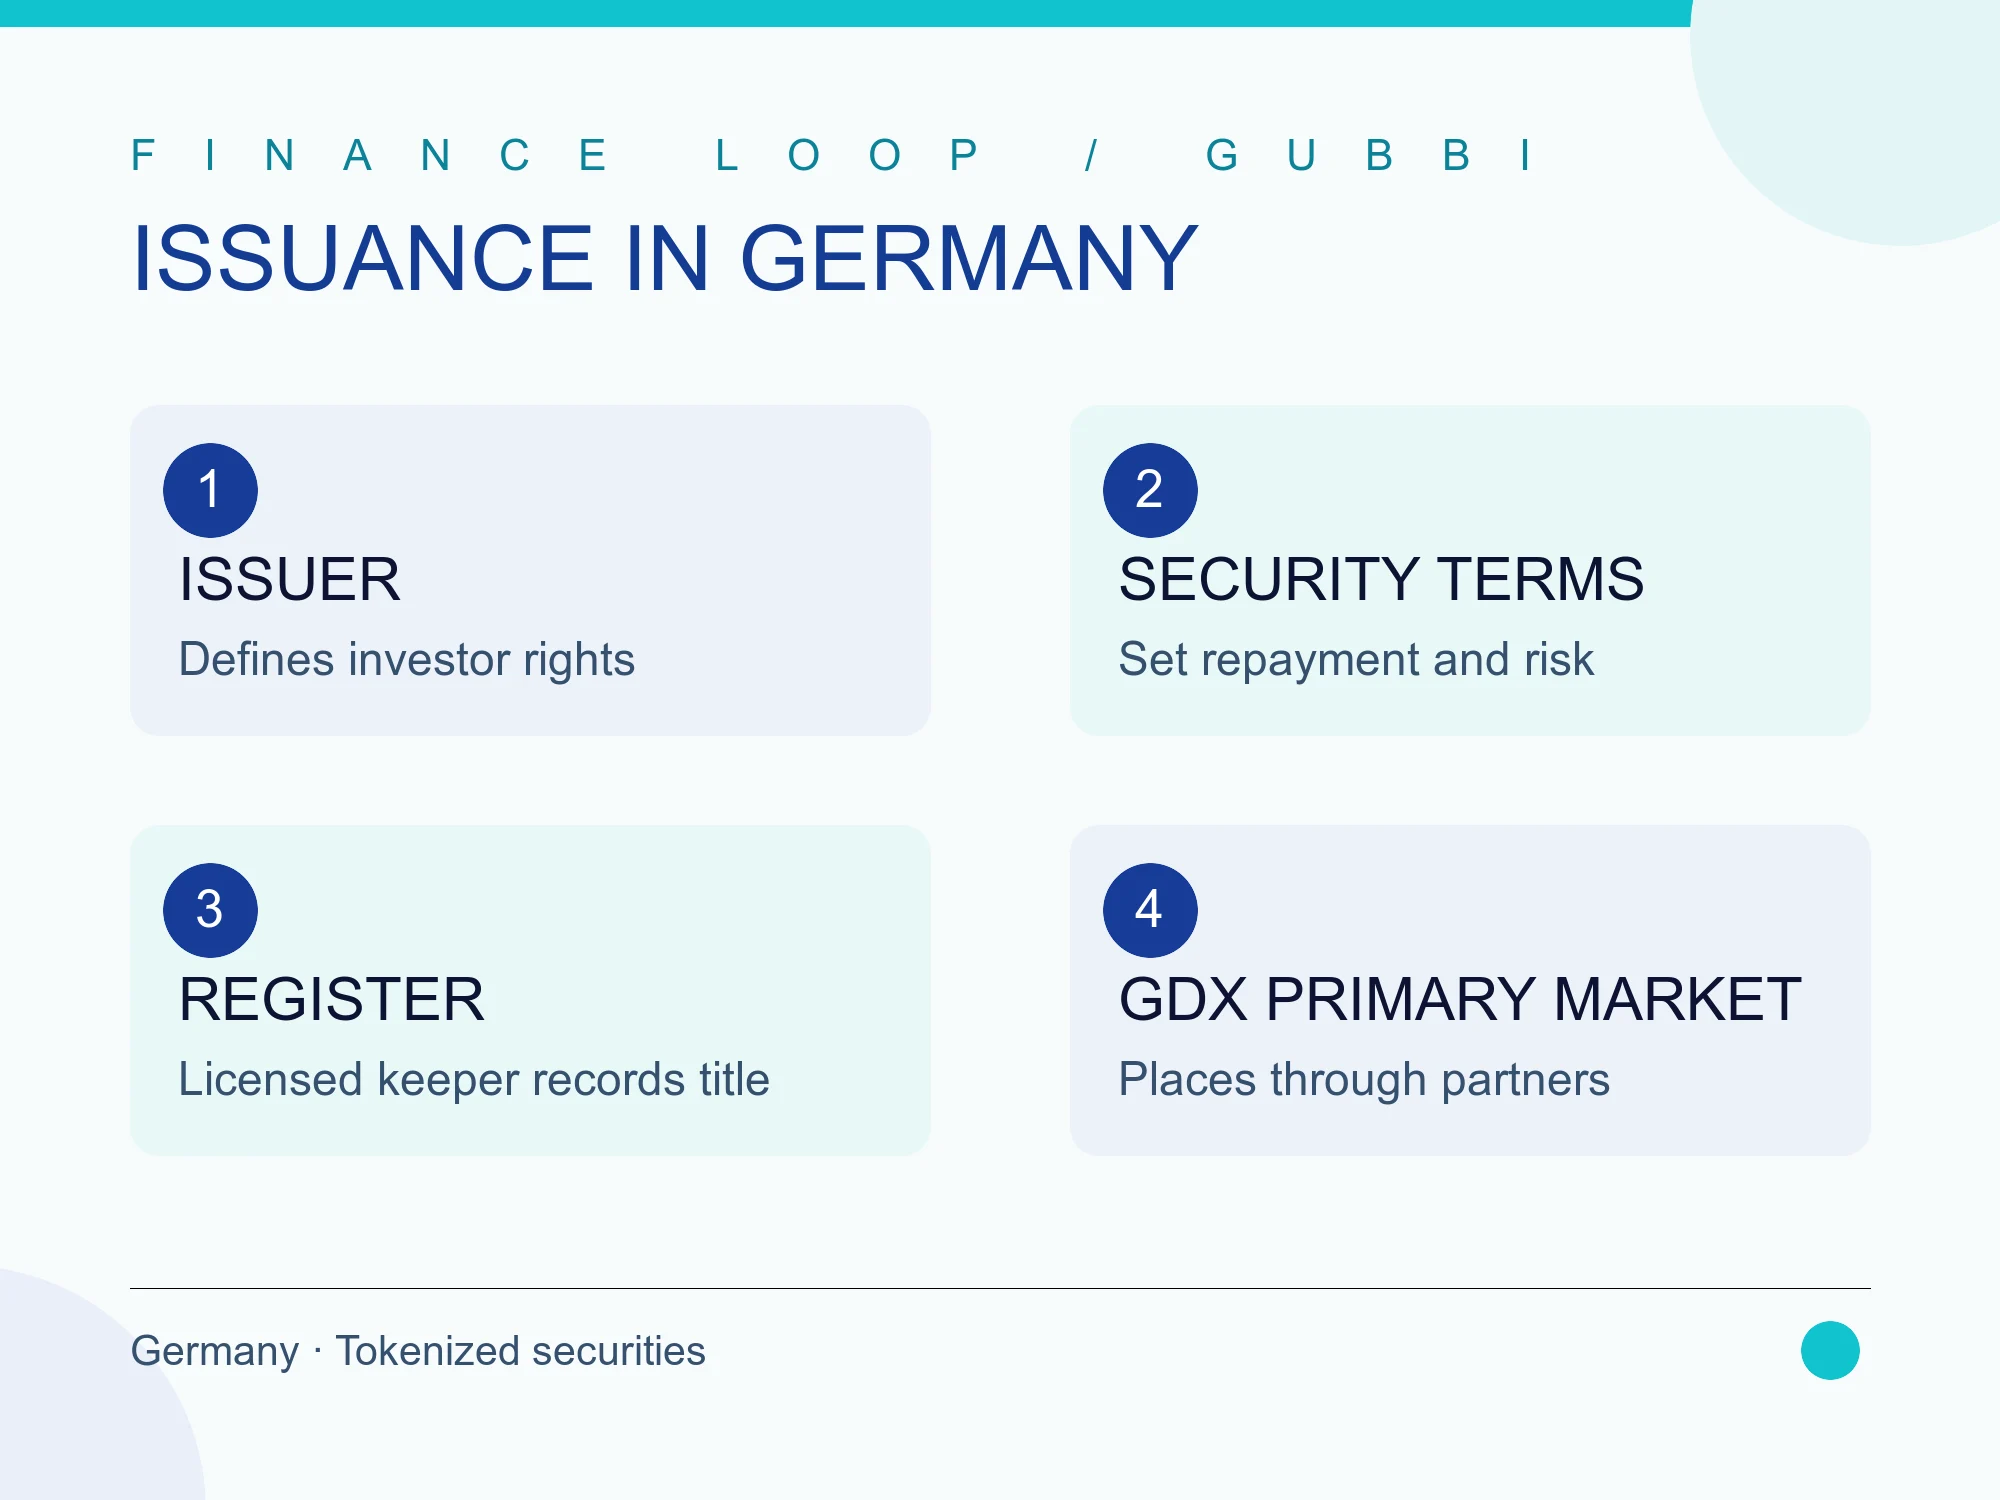
Start with the security, not the token
The issuer first decides what investors will own: a repayment claim, interest, participation in a fund or another defined right. That decision sets the disclosure, prospectus and investor eligibility questions. Technology cannot replace the security terms. Tokenized bonds are one possible form; tokenized securities explains the wider legal category.
For a German electronic security, the Electronic Securities Act (eWpG) provides the register framework. The issuer and its advisors must determine which instrument and register route are suitable for the transaction.
Who records ownership?
A crypto security under the eWpG is entered in a crypto securities register. The register keeper is a regulated party, separate from the issuer's marketing or technology provider. Gubbi says that activities requiring a license are performed through its licensed partners. This distinction matters when an issuer compares a tokenization platform, a register keeper and a distributor. Gubbi includes issuance in its 360° Value Chain (in German).
Before launch, the issuer needs agreed responsibilities for issuance data, investor onboarding, custody or wallet access, transfers and ongoing reporting. The product may be digital, but each step still needs an accountable operator.
How GDX Primary Market enters the issuance process
GDX Primary Market's issuer information (in German) describes onboarding, review, placement and reporting. GDX Primary Market is operated by Gubbi Protection GmbH and works with licensed partners for regulated services. Its role is to connect a prepared issue with banks, financial advisors and other distribution partners in Germany. The next step for an issuer is therefore a placement plan: which investors may buy, through which channel, and with which documents?
Gubbi and its platform do not turn every asset into a suitable public offer. The structure and distribution depend on the instrument and the permissions of the parties involved.
What should an issuer prepare before a first call?
Bring the proposed security terms, target investors, intended issue size, existing legal advice and an outline of the distribution route. Ask who keeps the register, who performs the regulated brokerage or advice, and what happens after issuance. Distribution of tokenized securities in Germany addresses the channel decision in more detail.
Upcoming tokenization events in Germany
Issuance, distribution and trading
Tokenized securities and Finance Loop
Finance Loop brings issuers, financial institutions and technology providers together around tokenization in Germany. Gubbi AG is a Finance Loop Premium Partner and contributes its experience with issuance and distribution.
Finance Loop is a professional network and has the goal of driving the adoption of emerging technologies in finance, such as AI, tokenization, stablecoins, and DeFi. Finance Loop helps its members build skills and personal networks in these fields: Investment & Digital Assets, Payments & Digital Money, and Risk & Compliance.